AMD’s Next Leap Requires More Than a Faster Chip
Data centers are accelerating as other markets diverge. AMD’s industrial reinvention, finances and customer equity agreements show what it takes to turn computing demand into shareholder returns.
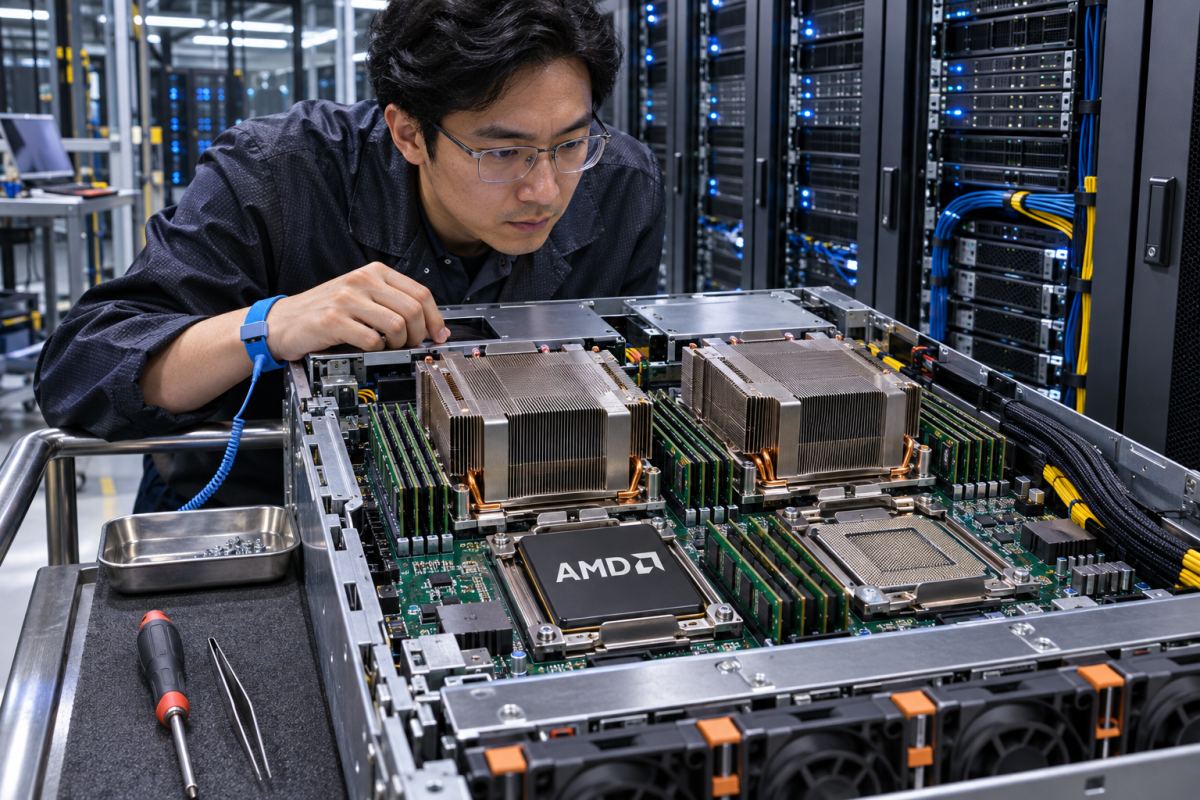
Winning a chip design is only the beginning. A customer must be able to obtain the processor, integrate it into a system and run useful software on it. Advanced Micro Devices has grown by solving those problems across personal computers, servers, graphics and embedded equipment. Its next expansion increasingly depends on delivering a broader computing platform, rather than a component judged in isolation.
AMD’s equity value was approximately $663.25 billion in the November 5, 2026 snapshot. The figure reflects expectations for a company whose data-center sales are rising rapidly, but whose customer devices and gaming businesses face different conditions. Understanding that contrast helps explain why the excitement around artificial intelligence is only part of the financial story.
An industrial reinvention over several decades
AMD was incorporated on May 1, 1969, and became publicly held in 1972. Its long history includes competing in processors and repeatedly changing how it obtains the technology and capacity needed to compete. The company’s survival and later expansion were not a straight line from a successful early product to today’s market position.
The 2006 acquisition of ATI added graphics capabilities. In 2009, the formation of GlobalFoundries separated major manufacturing operations into a joint venture, marking a fundamental change in AMD’s industrial structure. The company increasingly concentrated on design while relying on outside manufacturers. That reduced the need to own every production facility, but made access to partners’ processes and capacity strategically important.
The acquisition of Xilinx, completed in February 2022, added adaptive computing products and expertise. These devices serve requirements different from ordinary PC processors, including specialized and embedded applications. The transaction broadened the portfolio while adding accounting assets, integration responsibilities and a wider set of customers. Diversification through acquisition creates opportunities, but it also changes the company shareholders need to evaluate.
Chair and chief executive Lisa Su now leads a business combining central processors, graphics and AI accelerators, adaptive products, networking and software. The pieces are related because customers buy working systems. A faster device can have limited commercial value if software compatibility, memory, networking or delivery becomes the constraint. Competing successfully requires coordinating more of that chain.
What the annual accounts actually show
For fiscal 2025, ended December 27, AMD reported revenue of $34.639 billion, compared with $25.785 billion a year earlier. GAAP operating income was $3.694 billion. Total net income reached $4.335 billion, including $4.269 billion from continuing operations and $66 million from discontinued operations. That separation matters because a disposed business should not automatically be treated as a recurring source of future profit.
The annual research and development bill was $8.091 billion. Outsourcing fabrication does not make product creation inexpensive. Engineers, software development and successive design generations require spending before their eventual commercial success is known. The company must sustain those efforts while customers evaluate competing products and decide when to adopt a new platform.
Year-end total assets were $76.926 billion, with only $2.312 billion of net property and equipment. The contrast with manufacturers that own large fabrication networks is substantial. Yet the balance sheet also includes goodwill and acquisition-related intangible assets. A relatively small factory estate does not mean all assets are cash, nor that the business can operate without major financial commitments.
Cash and equivalents were $5.539 billion, with $5.013 billion in short-term investments. Operating cash flow from continuing activities was $6.493 billion during the year. These figures help distinguish reported earnings from the cash available to support research, inventory and other obligations. Product growth can require more working capital before customer payments arrive.
Data centers pull away from the rest
The latest reported quarter ended September 26, 2026, with results released on November 3. Revenue reached $13.377 billion, up 45% from a year earlier. GAAP operating income was $2.832 billion and net income $2.428 billion, with diluted earnings per share of $1.46. The adjusted earnings figure of $2.09 per share belonged to a different, non-GAAP presentation.
Data Center revenue reached $8.546 billion, up 97%, supported by EPYC processors and the launch of Instinct MI450-series accelerators. That made the segment the clear growth driver. AI systems can use both server processors and accelerators, giving AMD several ways to participate in customer investment. The opportunity is broader than assuming that every additional data-center dollar purchases the same type of chip.
The Client and Gaming segment generated $3.722 billion, down 8%. Client revenue rose 7% to $2.949 billion, while gaming fell 40% to $773 million. Embedded revenue increased 29% to $1.109 billion. These figures resist a simple description of universal growth: a strong server and AI cycle can coexist with weaker console-related or graphics sales.
GAAP gross margin was 54%, and operating income grew faster than revenue. Greater scale can spread some development and operating expenses across additional sales. However, a favorable product mix is part of the explanation, and spending must continue for future generations. A growing quarter demonstrates operating leverage under its actual conditions, rather than proving that every future sales increase earns the same incremental margin.
Customer agreements can also affect shareholders
An important financial complication lies in warrants issued to two customers in October 2025 and February 2026. Each agreement can allow the purchase of up to 160 million AMD shares at an exercise price of one cent. Vesting and exercisability depend on purchase milestones, stock-price targets and technical and commercial conditions. Those maximum amounts were not all shares already exercised or unconditionally issued.
The arrangements connect commercial adoption to ownership economics. The grant-date value of warrants expected to vest reduces revenue as qualifying customer purchases are recognized. Subsequent changes in the related liability’s fair value can affect other income and expense. The accounting is therefore more complicated than calling the entire arrangement either a sales discount or an ordinary operating cost.
During the third quarter, AMD recorded a noncash charge of approximately $1.2 billion, primarily from remeasuring the warrant liability. The absence of an immediate cash payment does not make the effect irrelevant: potential share issuance and ownership dilution remain important to existing holders. Investors must assess both the business obtained and the claims offered in exchange for it.
A platform strategy still needs a supply chain
By September 2026, total assets had reached $94.812 billion. Cash and equivalents were $7.404 billion, short-term investments $8.372 billion and inventory $11.463 billion. Net property and equipment were $3.929 billion. These balances show a company expanding resources and product commitments while maintaining a different manufacturing model from a business owning the full production chain.
Long-term debt was $7.079 billion. Goodwill of $25.470 billion and acquisition-related intangibles of $15.101 billion also occupied a large part of the balance sheet. The values reflect past transactions and expected benefits, not money waiting to be spent. Future results must justify the capabilities acquired as well as the engineering developed internally.
Outside manufacturing partners, including TSMC, provide essential production capabilities. Advanced packaging and memory availability can constrain deliveries even when a processor design is competitive. Export restrictions can affect which products reach particular markets. Dependence on partners is the other side of a model that avoids financing every fabrication plant directly.
Software and qualification create another hurdle. Customers need supported tools, compatible applications and reliable operating experience before shifting important workloads. Winning a place in the development plan of a large customer is valuable, but it must become delivered, usable infrastructure. Technical performance, commercial terms and the practical cost of adoption all influence the result.
AMD said on November 10 that its sixth-generation EPYC SP7 server processors were generally available and that systems using them were shipping from server manufacturers. It described Microsoft Azure and Oracle Cloud Infrastructure instances as forthcoming. Two days later, AMD introduced the MI450X as another option for its Helios AI systems, with 288 GB of HBM4 memory per accelerator, and reported MI455X inference measurements under specified test conditions. These are product and company-reported performance announcements, not evidence that every prospective customer has deployed the systems or that the projected revenue has been earned. They sharpen the commercial test facing AMD: turn a broader CPU and accelerator portfolio into qualified systems, dependable supply and profitable sales.
The expectations inside AMD shares
Common shares trade on Nasdaq under AMD. The November 5 market value equaled approximately 153 times total reported fiscal 2025 net income. That historical multiple incorporates a year with discontinued-operation income and accounting effects from acquisitions. It is not a forecast earnings ratio, and it cannot summarize the rapid changes visible in the latest quarter.
Management’s fourth-quarter outlook called for approximately $17 billion of revenue. That was guidance, not a result already achieved. Investors must judge whether growth can become durable earnings per share after research, competitive responses and customer-related equity arrangements. A larger business and a larger benefit for each existing shareholder are connected, but not identical, outcomes.
AMD’s history shows a company willing to change its industrial structure and product range to remain competitive. Its present opportunity is to make those capabilities work together as customers build new computing infrastructure. The lasting test is delivery: useful systems, reliable supply and financial returns that remain attractive after counting the full cost of winning and serving the customer.